
What to Know About First-Time Home Buying
July 30, 2026
So while you do not need to be a first time buyer to get an FHA loan you may need to meet that definition to qualify for down payment help. That said, "first time buyer" is a flexible description as we discover below.
Do you need to be a first-time homebuyer to secure an FHA loan?
No. Homeowners can apply for another FHA mortgage if they meet credit, income, and debt requirements. The new loan must be for a property the buyer uses as their main residence.
How do the FHA and HUD define a first-time homebuyer?
The FHA and HUD definition of a first-time buyer is one who has not owned a main home within 36 months prior to case number assignment. Former homeowners who sold properties over three years ago qualify.
Single parents who only shared property ownership with a former spouse also qualify. Displaced homemakers who previously shared a home with a spouse meet the standard as well. Remember that what counts at the FHA and HUD may not be the same for a state/local program. Your experience may vary.
What do borrowers need to know about first-time home buyer status?
State and local governments often require first-time buyer status. Program grants and secondary loans that cover closing expenses demand compliance with the three-year standard. If you haven't owned property in three years, you may qualify, but the home you want to purchase with the new loan must be your intended home address.
Also, down payment assistance is not standardized from state to state. The details of one state's program may not match another and if you are relocating to a new area it's not safe to expect the same standards in your new housing market.
What credit scores do applicants need?
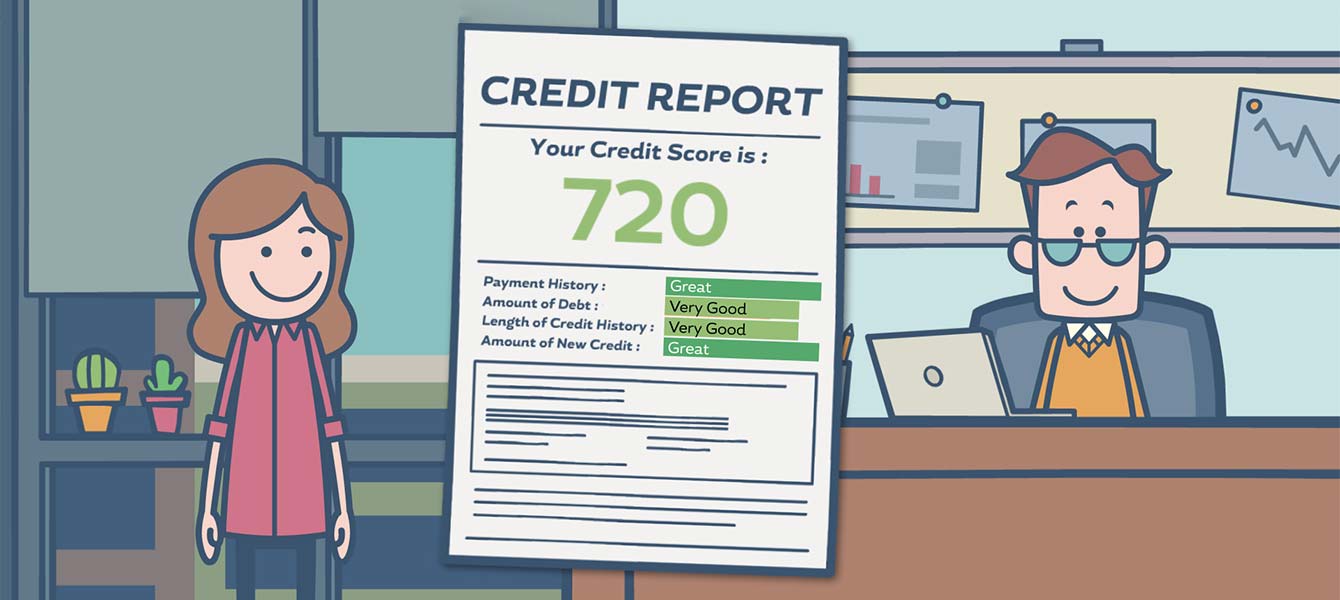
Scores of 580 or higher require a 3.5 percent down payment. Scores between 500 and 579 require a 10 percent down payment.
Applicants with credit scores below 500 do not qualify. Borrowers who put down 10% or more in any circumstance may qualify to have their FHA mortgage insurance removed after 11 years. These guidelines affect loan approval, but they may not be applicable to the state/local down payment assistance program, so you'll need to check which guidelines apply.
What work history must applicants show?
Lenders require verification of two years of employment in order to qualify for an FHA mortgage. Higher education, trade school, and military duty count toward this timeframe. These standards are not necessarily applicable to down payment/closing cost assistance, but be sure to check program guidelines.
How do debt levels affect approval?
Lenders compare monthly debt payments against gross monthly earnings. Housing costs should not exceed 31 percent of earnings. Total monthly debt obligations should be at or below 43 percent of gross income in typical cases.
FHA Loan Articles
August 31, 2026First-time homebuyers stepping into today's housing market sign closing paperwork required by federal consumer protections that took over forty years of regulatory battles, legal overhauls, and paperwork redesigns to build. Everyone buying a single-family house today with a forward mortgage receives a modern Closing Disclosure three business days before signing their final loan paperwork.
August 27, 2026Getting a home loan after a Chapter 7 or Chapter 13 bankruptcy isn't easy, but it is possible, thanks to FHA loan rules found in HUD 4000.1. Typically, you'll need to wait out a minimum time called a seasoning period before you're allowed to apply for new credit, and FHA loan rules say the lender must review your new credit established in the meantime as a condition of loan approval. What do you need to know about getting an FHA mortgage after bankruptcy?
August 24, 2026A reverse mortgage lets homeowners age 62 or older, with or without heirs, cash out their home equity without taking on a monthly mortgage payment. The FHA Home Equity Conversion Mortgage lets qualifying borrowers take equity in cash with loan balance due only after the borrower dies, moves out, or sells the house. Is this type of loan right for someone who has no heirs to inherit the home?
August 19, 2026Homebuyers who have enough cash for a down payment still need to consider their full financial picture before choosing between a conventional mortgage and an FHA loan. Having cash on hand changes the math for both options, but savings alone won't make a conventional loan the automatic winner. Credit scores, current debt, and the type of property you want to buy all determine which loan will cost less over time.
August 13, 2026Looking for a new home? Choosing the right mortgage is an important early step in your journey toward homeownership. There are many options, depending on your circumstances. You may qualify for conventional financing, an FHA mortgage, a USDA loan, or even a zero-down VA mortgage. Finding the right match depends heavily on credit, location, and the size of your down payment.